Monday, September 21, 2026

Workers who move to firms with higher well-being scores take more sickness absences, without changing healthcare usage

By Riccardo Di Francesco, Peter Hull & Seetha Menon.

"We study how firms’ orientation toward employee well-being shapes the health of their workers. Because this orientation is not directly observable, we measure it from the language Danish firms use in their public disclosures, applying language models to construct a firm-level well-being salience score. We link this score to population-wide administrative registers of health and sickness absence over 2013–2022, and exploit workers’ mobility between firms to estimate how workers respond to a change in the salience of their employer. We find an asymmetry: workers who move to higher-salience firms take substantially more sickness absence, while their use of health care does not change. Because worsening health would raise both, the absence response suggests a behavioral change rather than deteriorating health. Broadly, our results show that firms shape not only worker health but how workers act on it, and that the language of routine corporate disclosure can reveal economically meaningful features of the workplace that administrative data leave unrecorded."  

So if you make it easier to take time off workers will do that even if they don't need it. This could happen if we had national health care. 

The Tragedy of Nikole Hannah-Jones (and the problems with public education)

By Alex Tabarrok.

"Nikole Hannah-Jones famously sent her child to a predominantly black/lower-income public school in New York City. Now her child says she shouldn’t have been used as political fodder.

The essay makes for hard reading and I acknowledge NHJ’s courage in writing about her mistakes and the cost to her child. The piece is raw and true when talking about her personal choices, but the larger story in which NHJ embeds her personal history is mostly false. The problem isn’t funding. The failures she documents are failures of management and accountability, not lack of resources. NYC spends upwards of $40k per pupil on average, the highest of any large district in the country. Moreover, schools in NYC with lower-income students get more than the average. PS 307, where NHJ initially sent her child, is currently funded at just over 52k per student, far above the national average.

Nationally, there haven’t been big gaps in funding within states by race or income for decades. NHJ has reckoned with her failing her own child but she has not yet reckoned with the failure of her entire educational philosophy.

The role of ideology in blinding NHJ is dramatic. NHJ’s daughter earns high grades in her math classes but she fails standardized tests. Most parents, especially conservatives, know what that means. The classes are a lie. But NHJ is blinded by ideology and assumes it’s the standardized tests that are biased. It’s only when her daughter demands to go to a better school that she and her daughter confront the truth:

Najya knew very little algebra and had huge gaps in many of the building blocks of math that she should have learned in elementary school, like mastery of long division and fractions.

The confrontation is almost disastrous:

My child’s confidence wilted like an unwatered plant. She started to develop an almost debilitating anxiety around taking tests. She became sullen at school and began to act out. For the first time ever, I got messages from teachers about Najya’s behavior.

Fortunately, Najya battles back and recovers but much more could be said here about the costs of social promotion, DEI and mismatch on the so-called beneficiaries.

Ironically, NHJ invokes the heroic history of Black Americans integrating schools to justify keeping her own child in a segregated one. Painful.

NHJ thought that she and her husband–politically connected, astute people who were not afraid to speak up–could do well for their daughter and the other kids in the school. But in the end she has written a great piece on why voice fails–even a powerful voice–in the absence of the threat of exit. Hannah-Jones could have saved herself some grief and her child a poor education by reading my post The tragedy of Jonathan Kozol.

It’s been said that Ayn Rand’s heroes don’t exist, but her villains do. Case in point. Hannah-Jones says that she and her husband “felt an obligation to make educational decisions based on the collective good.” But she wasn’t just sacrificing herself for her ideology; she was sacrificing her child, who had no choice in the matter. “I don’t think she’s deserving of more than other kids,” she said in 2017. Nearly a decade later, Najya reminded her that in the abstract your child may not deserve more than other children, but she is nevertheless entitled to expect more from you. “Sometimes I wish instead of always thinking about other kids, you would have thought about me.” You don’t have to be a Randian to think that your child should not be sacrificed to the collective good, but it doesn’t hurt."

Sunday, September 20, 2026

College campuses need to be liberated from their administrators

Higher ed is being strangled by absurd and costly rules. What message is that sending to students?

By Barry Lam. He is a philosophy professor at UC Riverside. Excerpt:

"The promise of digital infrastructure is to be able to do bureaucratic tasks more cheaply and efficiently. In principle, just like spending on administrative staff should make the essential functions of administration less burdensome, spending on software should make spending on administrative staff less essential.

But in higher education the opposite has happened. Millions and millions of dollars are being spent on digital infrastructure and the hiring of administrative staff who must oversee and mitigate problems caused by the digital infrastructure itself.

The University of California system promised that $170 million in spending on a single digital infrastructure project would cut administrative bloat by $753 million over its lifetime. Instead, the project took seven years and ballooned to $942 million in cost — and the finished project was so poorly designed and difficult to use that an entirely new IT unit had to be created just to keep the software functional. The savings on staffing were zero."

The Shaky Evidence That Flock Cameras Reduce Crime Rates

Flock has been promoting a recent study of its cameras' impacts on car theft. But the paper didn't demonstrate a causal effect.

By Autumn Billings of Reason

"Do Flock cameras actually reduce crime? A new analysis by the Institute for Justice casts doubt on Flock Safety's claims that its automatic license plate readers (ALPRs) significantly reduce car theft and increase clearance rates. 

Flock Safety has been promoting a working paper that examines whether the company's controversial and hotly debated cameras improve outcomes for motor vehicle theft. To test the effects of Flock's surveillance network, the study uses data from 216 agencies that began using Flock in the period from 2017 to 2023, and 3,108 agencies that did not. The authors then evaluated the cameras' effects on monthly motor vehicle thefts, arrest rates for motor vehicle theft, and the recovery time of stolen cars following ALPR deployment.

The study's findings include an 11 percent drop in motor vehicle theft, a 15.9 percent increase in motor vehicle theft arrests, and a reduction of 0.28 days in the median recovery time for some stolen cars. The authors concluded that "fixed ALPR deployment is associated with lower theft and higher [arrests], alongside a modest reduction in recovery lag among recorded recoveries."

But the data aren't actually that clear, according to a new analysis from the Institute for Justice (IJ), a libertarian law firm and home of the Plate Privacy Project

IJ Senior Researcher Analyst Matthew West found that motor vehicle thefts and arrest rates in those jurisdictions were already trending in the favored direction months before Flock's cameras were ever in use. Unsurprisingly, many of the places that chose to deploy ALPR systems did so when experiencing high levels of vehicle theft, and engaged in crime-fighting initiatives beyond partnering with Flock. Because the study doesn't compare places on similar trajectories, it is unclear how much credit the cameras, as opposed to those other initiatives, deserve for causing motor vehicle thefts to fall and arrests to rise. 

"Because there were already differences in arrests and thefts trends before ALPR deployment, we don't know if the differences in ALPR deployment were caused by ALPR deployment," West explained in a statement

West goes on to point out that the authors were able to obtain an 11 percent drop in motor vehicle theft only "when the data are weighted in favor of agencies that had a bigger problem to begin with." By contrast, if "the data are instead averaged across all agencies (or weighted by population), the study finds no statistically significant change" in the number of thefts.

The study's data have other complications that the authors did not fully account for. One is the COVID-19 pandemic lockdowns, which impacted both the level of crime and the number of people driving across the country. Another is the viral "Kia Challenge" on social media, which led to increased Kia and Hyundai thefts. Such "events may have contributed to motor vehicle theft rising and falling at different times in different places," writes West, further complicating whether ALPR cameras did, in fact, cause favorable changes in the data. 

hese criticisms don't necessarily mean the study's results are wrong, but they do show that the full picture hasn't been explored.

Flock has been using the working paper's results to defend its cameras against an ongoing national backlash. But as much as the company may wish otherwise, the scrutiny of ALPR surveillance technology is far from over."

Saturday, September 19, 2026

A 5 Percent Wealth Tax Would Destroy a Lot More Than It Raises

 By Jack Salmon. Excerpts:

"the billions of dollars in wealth held by the almost 1,000 billionaires in the U.S. isn’t cash that is being hoarded under a mattress waiting to be taxed. For instance, Elon Musk’s roughly $900 billion fortune is mostly stock held in SpaceX and Tesla."

"Musk’s personal fortune represents only about one-third of the combined value of the companies he has founded."

"The remaining two-thirds is represented by factories, equipment, intellectual property, business assets, and claims held by other shareholders, including pension funds, mutual funds, and ordinary Americans who own shares directly or indirectly. The companies also employ tens of thousands of workers whose wages support household incomes and consumption.

For other billionaires, the share of wealth kept for themselves versus the share granted as value created for wider society is even larger than that of Musk. Mark Zuckerberg’s personal fortune represents about 13 percent of the market value of Meta. The other 87 percent is owned by shareholders, ordinary investors, or represented as data centers, servers, other productive assets, and nearly 79,000 employees.


In other words, the wealth of billionaires is a small share of the trillions of dollars in private wealth that they have created for millions of ordinary American’s. The free enterprise system rewards this kind of entrepreneurial activity and innovative behavior that in turn promotes productivity and growth. Removing these rewards by confiscating their personal assets and handing them over to the state would instead punish such activity.

A 5 percent wealth tax is a 99 percent income tax

The second thing to recognize is that the proposed 5 percent tax on wealth is a much larger tax on the returns of investments.

But we also have to account for the invisible tax that we all pay—inflation. Once inflation is factored in, market returns drop to 5.48 percent. At that level, the wealth tax is a 91 percent tax on investment returns. If we also assume that capital gains taxes are applied to dividends, then the after-tax return drops to just 5.05 percent. In this case, the wealth tax is effectively a 99 percent tax on investment income.

A 99 percent tax on investment income will have a significant impact on the incentives of investors. One of the incentives that will undoubtedly change is that people will take less risks. Low risk investments have lower rewards, and this will be felt by everyone, not just the billionaires that the policy targets.

Slower capital formation, weaker productivity, lower wages and fewer opportunities for workers and businesses affect all workers and consumers, not just wealthy ones.

We already have a wealth tax of sorts

As Stanford economist John Cochrane recently pointed out on his Substack, the U.S. already taxes wealth in certain circumstances. For example, the estate tax applies to the assets of the deceased when it is passed onto an heir.

Importantly, I should point out that a tax on the transfer of property is very different to a tax recurring tax on property ownership. The Supreme Court has also made a strong distinction between these types of taxes too, as it considers the estate tax an indirect excise tax on the transfer of property.

As Cochrane points out, the estate tax attracts a significant amount of perfectly legal avoidance. Although the tax applies at a much lower threshold than the proposed wealth tax, at $13.99 million, the Treasury estimates, that combined with gift tax receipts, the estate tax raised $29 billion in revenue in FY2025, or less than 0.1 percent of GDP.

Even a study published by supporters of a wealth tax found that the estate tax collects just 300-to-400ths of a percent annually of the Forbes 400 wealth.

The revenue gain is about $200 billion a year

So how much revenue do proponents of a wealth tax suggest it would raise if implemented in the U.S.?

French economists Emmanuel Saez and Gabriel Zucman estimate that a 5 percent wealth tax will raise $4.4 trillion over 10 years. To get this figure, they assume a tax evasion rate of 10 percent. This implies an elasticity of taxable wealth around -2. This assumption is significantly out-of-whack with the bulk of economic literature.

Evidence of savings effects based on Norwegian micro data estimate elasticities of taxable wealth around -7 under a comprehensive tax base. Similarly, evidence from Switzerland using cantonal variation finds that a one-percentage-point reduction in the wealth-tax rate increased reported taxable wealth by at least 43 percent after six years.

One 2021 journal article used rich administrative data from Colombia and a government-designed program for voluntary disclosures of hidden wealth to estimate the behavioral effects of wealth tax. The authors found that two-fifths (40%) of the wealthiest 0.01 percent evade taxes, with these evaders concealing one-third of their wealth offshore.

Using Danish administrative data, Jakobsen et al. find that reductions in the wealth tax increased taxable wealth by 31 percent among the very wealthy over eight years. Their estimates incorporate saving, portfolio and asset-composition responses, legal avoidance, and possible evasion of self-reported assets. The net-of-tax rate elasticity is therefore estimated at around -11.

With these estimates in mind, budget scoring organizations often use more realistic elasticity estimates that are more aligned with the economic literature. For example, the Tax Foundation models wealth tax proposals using a semi-elasticity assumption of -8, while Penn Wharton applies semi-elasticities of evasion and avoidance around -9.

If we replace the elasticity assumptions of Saez and Zucman with a more realistic semi-elasticity of around -8, then the revenue raised by the tax drops from $4.4 trillion to $3.3 trillion over 10 years. This isn’t an outlier assumption. In fact, Sanders and Warren used a 33% avoidance assumption in their 2020 wealth tax campaigns.

Factoring in baseline avoidance in the existing tax system and stronger behavioral responses, tax scholar Kyle Pomerleau applies an elasticity of -13. This results in a 10-year revenue yield of $2.3 trillion, or roughly half the Saez-Zucman figure. This amounts to a little over $200 billion a year in additional revenues, or about 10 percent of current deficits.

A high price for the U.S. economy

A 5 percent wealth tax isn’t just a tax on billionaires, it is a tax on investment, a tax on risk-taking, a tax on capital accumulation that drives productivity, higher wages, and job growth. The people who ultimately bear those costs would include workers, consumers, retirees, and the millions of ordinary Americans whose savings are invested in the companies billionaires helped build.

Wealth is not cash sitting idle in a bank account. It is the factories, companies, technologies, and investments that generate future income for millions of people. Taxing wealth at punitive rates may satisfy a desire to punish the rich, but it risks shrinking the very economic base from which future prosperity will come.

Let’s not tax away our productivity, innovation, and growth for the sake of political symbolism."

Friday, September 18, 2026

Rideshare Licensing Fails the Consumer Protection Test

By Ryan Bourne and Nathan Miller of Cato.

"Occupational licensing is sold as consumer protection that screens out incompetent or dangerous workers. Today, about 22 percent of the American workforce needs a government license to do their jobs, and that safety and quality argument is what state and local lawmakers use to justify the entry barriers, licensing fees, and training hours that typically accompany it.

The trouble is that the claimed benefits have historically been difficult to test or measure, so the debate over whether licenses really protect anyone was fueled mostly by anecdotes. That’s why a new NBER working paper by Jonathan Hall, Jason Hicks, Morris M. Kleiner, and Yun taek Oh is so interesting. It leverages Uber data and finds no consistent evidence that a government occupational license improves riders’ ratings or drivers’ behavior on the road. The results suggest that, once a platform is already screening and monitoring its drivers, licensing adds no detectable, additional consumer protection.

Why Uber Is a Good Testing Ground

Uber’s vast datasets from trip tracking and consumer ratings have proven a goldmine for researchers on an array of economic questions. 

One of us has written before about how data on female and male drivers’ earnings gave good insights into non-discriminatory causes of gender pay gaps. Now similar data can be used to examine the effects of occupational licensing laws for rideshare drivers.

Uber dispatches drivers mainly by proximity. So when a licensed and an unlicensed driver are both near a rider, which one is dispatched is essentially a coin flip. The researchers use that quasi-random assignment along with data Uber collects about the ride quality, such as the rider’s star rating and telematics data on how carefully the car was driven (by measuring things like hard braking and hard acceleration, which are tied to greater crash risk).

The authors exploit two settings that allow a test of licensing’s effects. First, New York City licenses rideshare drivers through the Taxi and Limousine Commission, which, at the time covered by the study, required a fingerprint background check, a defensive-driving course, and a 24-hour vehicle for hire course and exam. Neighboring New Jersey does not have these requirements, yet drivers from both areas serve the same New Jersey riders. 

Second, in 2017, Texas preempted local occupational licensing of rideshare drivers, abolishing Houston’s restrictive licensing requirements. That let the researchers compare previously licensed drivers with those who entered the market after the entry restrictions were lifted.

The researchers sampled 213,000 trips in the New York area from April to August 2017 and nearly 497,000 in Houston from September 2017 to January 2018 to look for differences between drivers with and without an occupational license. They checked for differences across seven metrics:

  1. Star rating (1–5)
  2. Proportion receiving ratings less than 5 stars
  3. Proportion receiving 1‑star ratings
  4. Prevalence of hard braking
  5. Whether more than 20 percent of brakes in a trip were hard brakes
  6. Prevalence of hard acceleration
  7. Whether more than 20 percent of accelerations in a trip were hard accelerations.

No Sign Licensing Helps Anyone

Across both metro areas, the paper finds no consistent evidence that licensing improved consumer outcomes. 

In the New York vs. New Jersey comparison, licensed drivers actually earned slightly lower ratings than their unlicensed counterparts—0.0228 fewer stars on Uber’s five-star scale, or less than half a percent off the unlicensed mean score of 4.78. 

Just one of the seven metrics compared came out in licensing’s favor. Licensed drivers logged fewer trips with a high share (20 percent or more) of hard-braking events, yet even that result didn’t survive robustness checks the authors undertook. It faded once the authors widened their sample window and swung wildly depending on whether they controlled for vehicle model and year. 

The results were similar in Houston. The researchers could not detect a statistical difference between the drivers who entered after deregulation and previously licensed drivers on all seven outcomes, despite the two groups differing sharply in experience (288 prior trips versus roughly 2,584 for the licensed) and age. This is strong suggestive evidence against the common fear that ending entry requirements would flood a market with worse providers.

When previously licensed drivers were instead compared with unlicensed drivers who had already been on the platform, the only differences ran against licensing: on three of the four driving-behavior measures, the previously licensed drivers braked and accelerated harder, with roughly 15 percent more of the high-hard-braking trips that flag risky driving.

Licensing Is a Costly Regime

A large body of research has already established the costs associated with occupational licensing. A strict licensing regime restricts entry into a market, thins the supply of workers, and thus tends to push prices up. 

As was summarized earlier this year in Cato’s Handbook on Affordability, stringent nurse-practitioner scope-of-practice rules raise child checkup costs between 3 and 16 percent, home improvement jobs are between 15 and 50 percent more expensive (depending on the job type) in states with the strictest home technician licensing regimes, and in one Virginia case study of hair braiding, the number of beauty shops grew 7 percent faster than in bordering states after Virginia deregulated in 2012.

So, although this paper doesn’t examine how occupational licensure affects fares, it’s reasonable to think based on existing literature that licensing rideshare drivers simply means fewer drivers and (absent substitute platforms outside the license regime) higher fares. This paper supplies evidence that despite that added cost, licensure often buys nothing in the way of improved quality or safety. 

Rideshare markets already have methods that go a long way to vetting drivers’ quality—reputational feedback, ratings, reviews, or the threat of account deactivation. That makes further government licensure redundant. The new paper is a strong complement to what Cato argued in our handbook earlier this year: the cheapest way to lower the price of a service is often just to let people provide more of it."

Thursday, September 17, 2026

The Food Revolution Nobody Planned

By Byron Carson.

"Long before policymakers conceived New York City Groceries, entrepreneurs fed people. They did it cheaply, and they made people better off in unimaginable ways. 

The approximately 63,000 grocery stores in the US (according to 2023 Census estimates) indicate a great deal of competition, which encourages owners to lower prices and improve food quality. The figure below indicates that these stores must also compete with approximately 650,000 domestic food and beverage retailers.

That’s a lot of competition, and it helps lower prices while producing a dizzying array of goods and innovation that makes the mythical land of Cockaigne look paltry. While higher prices understandably attract attention — recent CPI data for food indicates a 3 percent rise over the previous year — innovation takes place in myriad ways that are easy to overlook.

Open-air marketplaces and food halls are just some of the ways people innovate. To clarify, think about the mundane problems associated with acquiring food. There are myriad transaction costs associated with finding a seller interested in selling what you want, assessing the quality of an item, trusting that the seller isn’t cheating you, and so on. Entrepreneurs develop public or open-air markets and food halls to earn profits, and they do so by lowering transaction costs for consumers and providing innovative services. 

Historical and modern examples alike indicate the extent of innovation. Since 1742, Boston’s Faneuil Hall, or “The Cradle of Liberty” (and later the Quincy Market), has provided organized spaces for people to buy and sell food in mutually beneficial ways. The Redding Terminal Market is now a popular indoor marketplace and food hall, but it developed from the open-air markets in Philadelphia during the late nineteenth century. Similar kinds of commercial activity even developed in New York, perhaps ironically, in places now being touted as sites for government-owned grocery stores. La Marqueta, or the Park Avenue Market, emerged from the haphazard commerce underneath a viaduct, where people sold goods to customers willing to pay for them. Such commercial activity expanded so much that by 1936, the city enacted a more orderly marketplace

Food halls, food courts, food truck parks, and similar ventures are now common, reflecting entrepreneurs’ efforts to earn profits by providing goods and experiences customers value.

On recent trips to Tampa and London, I learned of two interesting examples of people developing food halls through private enterprise. In Tampa, the Oxford Exchange (opened in its current form in 2012) was once home to an arcade of shops in the 1920s. It was converted from a bookstore in the 2010s and now hosts several dining rooms, a coffee and wine bar, lounges, meeting spaces, and shops. London’s Mercato Mayfair (one of several food halls owned by Mercato Metropolitano) is located in a deconsecrated church and houses various food and beverage vendors.

From my brief visits, these places seem like vibrant focal points where eating is perhaps the least interesting thing to do. They offer comfort and service, novel and quality foods, places to meet, and more. The profit motive and the search for innovation, not governmental food policy, drive these efforts.

WorldFoodTrucks offers another case of private food innovation. Located in Kissimmee, Florida, WorldFoodTrucks is the first and largest food truck park in the US, where customers can find more than 100 trucks, each offering different culinary options, including more than 80 world cuisines. The park is open every day of the year (until 4 am on weekends), and its operators report serving more than 13 million customers since the park opened around 2023. Not only does the park offer food, but it also provides a convenient and inexpensive way to feed larger groups of people with interesting cuisine at corporate and celebratory events, such as graduations and weddings. Such market-driven opportunities are innovations because they satisfy several goals people value beyond simply providing cheaper food. 

The economist Steven Horwitz wrote that grocery stores are indicators of American progress. We should broaden these indicators to include food halls, food trucks, and other ways entrepreneurs try to feed people. Such progress benefits picky eaters, the fitness-conscious, people who want to grill out on a nice day, those trying to meal prep for the week, people making dinner for date night, those preparing a family meal on a tight budget, and many others. Progress is progress for rich and poor alike, and it serves myriad individual goals.

Rather than devise policies that consistently fail to make people better off, perhaps we should understand how entrepreneurial activities actually put food on the table and make people better off in ways they value."


Wednesday, September 16, 2026

Health-care costs for typical Canadian family will reach over $21,000 this year

By Nadeem Esmail, Nathaniel Li and Milagros Palacios of The Fraser Institute.

The Price of Public Health Care Insurance, 2026

  • Canadians often misunderstand the true cost of our public health care system. This occurs partly because Canadians do not incur direct expenses for their use of health care, and partly because Canadians cannot readily determine the value of their contribution to public health care insurance.
  • In 2026, preliminary estimates suggest the average payment for public health care insurance ranges from $6,464 to $21,115 for six common Canadian family types, depending on the type of family.
  • Between 1997 and 2026, the cost of public health care insurance for the average Canadian family increased 2.3 times as fast as the cost of food, 1.7 times as fast as the average income, and 1.5 times as fast as the cost of shelter. It also increased much more rapidly than the average cost of clothing, which has fallen in recent years.
  • The 10 percent of Canadian families with the lowest incomes will pay an average of about $637 for public health care insurance in 2026. The 10 percent of Canadian families who earn an average income of $88,572 will pay an average of $8,644 for public health care insurance, and the families among the top 10 percent of income earners in Canada will pay $66,350.


Tuesday, September 15, 2026

The cost of lighting has decreased by over 1000x

Tweet from Paul Graham

"One data point in technology making everyone richer: the cost of lighting has decreased by over 1000x."

Image  


The Tax Gains from Moving Across State Lines

Comparative tax burden · Tax year 2026

By Daniel Di Martino of The Manhattan Institute

"Americans have been moving from high-tax states to low-tax states for a long time, but the trend has become more acute since the Covid-19 pandemic hit the world in 2020. The increasing availability of remote work allowed many workers to move elsewhere and keep their jobs, and many companies also chose to relocate or reduce office occupancy. In addition, Americans are increasingly self-sorting according to political preferences. Most coverage of this trend has focused on the rich and how much they have to gain by moving from high-tax to no-income-tax states. Obviously, multimillionaires can keep more of their income if they move from a high-tax jurisdiction like New York City to Palm Beach, where there is no state or local income tax. My new income tax tool shows that not only the rich, but also low- and middle-income Americans, have a lot to gain from moving across state lines.

Take a couple earning $120,000 in New York City. The husband has a decent job paying $100,000, and his wife makes $20,000 working part-time. They have two children still in school. That couple does not benefit from itemizing deductions in their federal tax return, so they take the standard deduction and owe $10,040 in federal income taxes. Since they have two minor children, they will receive a $4,400 child tax credit to offset their tax liability.

Since they both have traditional jobs, their employers will owe $9,180 in Social Security and Medicare payroll taxes, while they will pay the same amount from their salary in payroll taxes, out of an effective compensation cost to their employers of $129,180. Since they live in New York State, they owe $5,186 in state income tax and $581 in payroll taxes for paid family and disability leave (both spouses contribute), but they also benefit from an $800 state child tax credit. Finally, since they live in New York City, they will pay an additional $3,727 in city local income tax.

All in all, out of a compensation cost of $129,180, the couple pays $32,693 in income and payroll taxes, or 25.3% of their income, leaving them with a take-home pay of $96,487. This couple faces an effective 36.3% marginal tax rate.

Would this couple be better off if they moved from New York City’s metropolitan area to the Nashville metropolitan area? Imagine the cost of this move is that the wife loses her $20,000 job and thus their income falls. This is a big hit, but they would pay no state and local taxes, and their federal income tax would also be much lower due to the progressive tax structure. Their federal income tax would be, net of the child tax credit, just $3,240, while their payroll tax liability would fall proportionally. Out of a new employer compensation of $107,650, this couple would pay a total of $18,540 in payroll and income taxes, for a take-home pay of $89,110. But every dollar goes much farther in Nashville than in New York City, as housing and everyday goods and services are cheaper—specifically, 14.48% cheaper. While New York City is 12.6% more expensive than the average U.S. territory, Nashville is 3.7% cheaper. Thus a take-home pay of $96,487 in New York City is equivalent to $85,690, while one of $89,110 in Nashville is equivalent to $92,534. In other words, even with a $20,000 lower nominal income, a married couple with two kids can still increase their real take-home pay by nearly 8% by moving across state lines. If they managed to keep their full income, or the wife later found another job, their real income would actually increase to $109,221—over $23,000 in additional real income, a 27% increase.

Now take the case of a middle-income single worker in Los Angeles, making $60,000 per year. His take-home pay would be $47,961. Say he lives in the Los Angeles metropolitan area, so his price-adjusted take-home pay is lower, at $42,219. If he moves to Orlando in Florida, his take-home pay will rise to $50,390, and adjusted for cost of living it would be $49,694. In other words, his after-tax pay rises by $2,429 per year, or over $200 per month, and his price-adjusted after-tax pay rises by $7,475, or over $600 per month—a nearly 18% increase.

While tax and cost-of-living gains are increasing with income, even the lowest-income earners in the United States can see increases of over 10% by moving across state lines, while the richest can see gains of over 30%." 

Monday, September 14, 2026

Does Bank Consolidation Harm Customers?

By Jeffrey Miron of Cato

"Antitrust policy presents a challenge for both libertarians and policymakers. On the one hand, competitive markets are good, which might suggest policy should limit firm mergers. On the other hand, mergers can have beneficial effects (such as economies of scale and scope, or disciplining unproductive firms), so broad opposition to mergers is likely counterproductive.

New research on bank consolidation offers evidence on this tradeoff. Contrary to the belief

that bank mergers reduce competition, increase borrowing costs, and limit households’ access to credit, … [the study finds that m]ergers have no meaningful effect on interest rates, approval rates, or late payments. Merged banks do not appear to use their increased size to charge borrowers more or restrict access to mortgages.

This may be due to

the intense competition in local mortgage markets. The typical county has more than 130 active mortgage lenders per quarter, and the median lender controls just 0.4 percent of its local market. Therefore, even when two banks merge, borrowers generally continue to have many other lending options. In some cases, local competition actually increases after mergers.

Whether these conclusions apply in markets with only a few firms, where mergers might substantially increase market concentration, is harder to know. But this evidence should still remind antitrust and banking regulators to consider the full range of effects from mergers, not just the impact on concentration per se."

By the Time Governments Are Regulating AI, They’re Regulating the Past

By Mark Jamison of AEI.

"AI is changing fast. And spreading fast. Both are problems for people seeking to regulate it.

Regulation works best when regulators understand what they are regulating. That is not the case for AI. Costs are collapsing, having dropped 1000-fold for large language models since 2023. At the same time, capabilities are expanding, business models are changing, and market leaders are turning over rapidly.

These dynamics create both opportunities and problems. Now almost anyone can use AI to manage their household or launch a business. But, as Bill Gates recently noted, they can also create deep fakes, launch phishing attacks, or break into internet sites, as happened to Hugging Face.

This also makes regulation hard: Rules written for the AI that regulators see today will no longer exist by the time the rules take effect.

Nevertheless, many people want regulations that would control AI. The EU has embraced what it calls comprehensive AI regulation, in which regulators judge the relative riskiness of AI applications and systems and then apply controls ranging from outright prohibitions to light-touch oversight. Some people are calling for mandated surveillance of AI users, restrictions on model capabilities, product standards, and computer code review. Gates recommends an international organization layered on top of national all-of-government regulators to oversee all AI risks people imagine. All of these approaches assume overseers who would control innovation.

While it is true that whenever a technology’s costs fall and its abilities grow, people use it more. Sometimes for evil. When Henry Ford put cars within reach of every family, some families created new businesses, but others became bank robbers. When internet service providers spread access across the country, e-commerce exploded, but so did criminal activity on the dark web. In these instances, successful regulatory responses were not to limit cars or the internet, but to use the technologies for regulatory purposes.

The examples of automobiles and the internet illustrate a path forward for AI policy: Let the technology evolve for the good it can do. At the same time, officials and entrepreneurs can protect citizens by developing their own innovations based on a deep understanding of the technologies and their markets.

Recent research published in the Journal of Economic Perspectives provides insights into AI and its markets. The researchers examined the AI most people use, LLMs. LLMs are growing in complexity, now operating in three layers: The Model Layer, where creators such as OpenAI and Meta design and train LLMs; the Inference Layer, where AI providers like OpenAI and Together AI host and run models to respond to user requests; and the Application Layer, where a large ecosystem of startups and established firms embed LLM capabilities into user-facing applications for accounting, legal, retail, and other services.

Activity in each layer has exploded in multiple directions. The Model Layer grew from 1 model in early 2023 to 668 by the end of 2025. There are curious dynamics in this layer. Open-weight models—which allow users to customize systems for specific tasks—charge users 90% less than do closed weight models. Open-weight providers effectively give away their models after spending billions in development and training. Despite what looks like bad economics, there are over twice as many open-weight models as closed-weight models, 449 versus 219.

Customers in the Model Layer also make choices that appear counter intuitive. Even though open-weight providers charge 90% less than do their closed weight counterparts, customers use closed-weight models more than twice as often.

The complexity doesn’t stop there. At the Inference layer, the number of providers grew from 30 to 90 in 2025. These providers largely host open-weight models and their non-price capabilities vary. Closed-weight model creators are more likely to have vertical relationships at this layer.

The growth and interplay of these two layers illustrate why controls can be counterproductive. They limit innovators’ abilities to experiment, meaning that there would be fewer models in both levels. Fewer models at this stage of development means fewer opportunities for customers to express their preferences. And it is unclear whether the two layers will remain separate.

Model diversity is growing in several ways. Measured by the Artificial Analysis Intelligence Index, 80% of the models fell between 0.1 and 0.29 on the scale at the beginning of 2025. By the end of the year, they fell between 0.22 and 0.61, an increase in spread of over 100%.

Market leadership changes often. In the Application Layer, the market leader for science-oriented models changed eight times in 2025, while the market leader for legal services changed five times.

What does this mean for regulators? The innovators, investors, and customers driving AI are creating tremendous value, estimated to be approaching $1 trillion. Regulatory controls handicap legitimate AI providers and create market opportunities for those less inclined to follow the rules.

The lesson isn’t that government has no role in AI’s evolution. It is that seeking to control AI is counterproductive. AI policy should let the government be a leading AI user without limiting legitimate users of AI. This is more like what good governance has always done: punish harmful conduct and protect citizens by adapting its own capabilities as the world changes."

Sunday, September 13, 2026

Mark Cuban and Healthcare Competition

Market competition accomplishes what decades of regulation haven't

By Ryanne Swanson & Raymond J. March of The Independent Institute

"Payton Herres successfully underwent heart transplantation surgery as a preteen. A year later, she began taking everolimus—a vital medication used to prevent her body from rejecting the transplant. Her insurance provider soon after denied coverage, leaving her with an indispensable but largely unaffordable prescription.  

Herres’ situation was alarming, but not uncommon. About 30% of Americans find themselves with uncovered treatment despite having health insurance. Unfortunately, medications for rare and/or chronic conditions, in some cases, have no generic alternatives. Not covering expensive but seldom-utilized treatments is an easy way for health insurance providers to cut costs. Unfortunately, these decisions can leave unsuspecting and financially strapped policyholders with few options. 

This is when Mark Cuban stepped in.  

Mark Cuban Cost Plus Drugs, an online pharmacy, helps many people in these situations access affordable medications, even without health insurance. Once unaffordable, his pharmacy now supplies Herres with a 90-day supply for about $300. In comparison, she likely faced bills ranging from $400 to $13,000 per month elsewhere.  

Cuban’s efforts are laudable, and in this case, probably lifesaving. And thankfully for many other patients, other efforts have been just as successful.  

Diabetic patients who need insulin can also face insurance gaps limiting access to life-prolonging medication. Like everolimus, insulin can be alarmingly expensive without coverage. Yet despite political promises and actions to make insulin more affordable, competition has quietly delivered for decades. Perhaps the most recognized example is ReliOn, which is available for about $25 a vial at Walmart pharmacies across the country. In some states, ReliOn is available over the counter.

During the nearly two-year GLP-1 shortage, many patients hoping to treat severe and complex forms of obesity were left without regular access to Ozempic, Mounjaro, and other injectable weight loss treatment options. Fortunately, copycat pharmacies and telehealth providers worked to help patients access generic-like treatments, even as insurance coverage struggled to keep pace with challenging market conditions. In this case, online pharmacies were so effective that they forced brand-name GLP-1 treatments like Zepbound to half their prices during a national shortage. Prior to the copycat and telehealth competition, some patients found themselves facing $1,000 prescription drug costs.  

These and other examples highlight a vital- but often overlooked- lesson about competition. The US healthcare industry is extremely regulated, particularly pharmaceuticals. And despite literal decades of political promises to expand coverage and lower prices, we’ve yet to see reform provide solid and consistent examples of either. Conversely, a relatively small online pharmacy and other unexpected retailers were able to provide what a larger health insurance provider and a torrent of regulations did not or could not- affordable medication. 

Sometimes a small dose of the right treatment is all you need." 

The never-ending ferry tale: Why Washington shouldn’t subsidize ferries

By Steve Swedberg of CEI.

"The Trump administration recently announced $664.8 million in federal grants for ferry infrastructure, including $28.2 million for North Carolina’s Cherry Branch Ferry Terminal. That caught my attention because before joining CEI, I was a transportation fiscal analyst for the North Carolina General Assembly. I had firsthand exposure to the North Carolina Department of Transportation (NCDOT) and its Ferry Division, including touring its vessels and shipyards.

The timing of the grant is particularly curious. North Carolina is now undertaking a performance audit of the Ferry Division, with the State Auditor required to report its findings by January 15, 2027. So as Raleigh asks how to make its ferry system more sustainable, Washington is sending North Carolina $28 million. That raises a more fundamental question: why is Washington paying for ferries?

North Carolina has spent years wrestling with the costs of its ferry system. Several routes historically carried passengers and vehicles without charging fares, while NCDOT reported insufficient funding for capital needs, including millions of dollars in unfunded vessel replacements. A 2017 General Assembly evaluation found opportunities to increase fare collections and reduce costs by adjusting fares and cutting low-demand crossings.

Meanwhile, the state’s ferry fleet has grown older and more expensive to maintain. Many vessels date to the 1980s and 1990s, and the Ferry Division has struggled to keep pace with maintenance needs. Its shipyards lack sufficient capacity to handle all necessary work, which has required NCDOT to turn to outside contractors for some repairs, at taxpayers’ expense.

After decades of subsidized ferry service, North Carolina is finally asking users to pay more. A 2026 law requires NCDOT to begin collecting tolls on all ferry routes by January 1, 2027, although the toll rates have not yet been finalized. That may be a step toward fiscal responsibility, but it comes after the state has accumulated substantial maintenance and replacement needs.

North Carolina isn’t the only state or recent grant recipient in this same boat. Alaska’s Marine Highway System acknowledges that fares alone don’t cover operating costs. Washington State Ferries recovered less than half of its operating costs from fares in 2024. Maine requires state support for half of its ferry operating costs and funds the system’s capital expenses, while Virginia’s Jamestown-Scotland Ferry charges users nothing.

These ferry systems operate under different circumstances and conditions. Yet in all cases, users do not pay the full cost to provide the service.

This is where economist and Nobel Prize winner Ronald Coase’s famous analysis of lighthouses provides enlightenment. The lighthouse was once the textbook example of a service that government supposedly had to provide because charging individual beneficiaries was difficult — the very definition of a public good. Coase challenged that conventional wisdom by showing that privately operated lighthouses existed and that ships could be conveniently charged for their use.

A ferry has an even more straightforward financing mechanism because its beneficiaries are readily identifiable, and passengers and vehicles can be charged directly. If a ferry provides enough value to justify its cost, its users should bear much more of that expense. This “user-pays” principle applies to transportation generally — even the gas tax is a user fee for road use.

And if policymakers believe a route is worth providing despite its inability to cover its costs, they should have to justify that decision to the taxpayers who fund it. There is no reason to make taxpayers in Ohio or Idaho finance a ferry in North Carolina.

The problem gets worse when the administrative state joins the financing equation. The Federal Transit Administration can cover up to 80 percent of eligible ferry capital costs, including vessels, terminals and related infrastructure. When Washington pays most of the capital bill, state policymakers have less reason to ask whether the people benefiting from that investment are willing to finance it.

Without that subsidy, policymakers would face harder questions: Is the route worth operating? How often should it run? What should users pay? How much should taxpayers subsidize? Is there a better way to provide the service? Federal subsidies make it easier for states to avoid answering those questions because someone else is footing most of the bill.

Ferry service may be important to the communities that use it, but that does not make it a federal responsibility. Federal subsidies shift the costs of state and local ferry service onto taxpayers who may never use it. Washington should stop turning local transportation choices into national obligations. Otherwise, the question, “Who pays the ferryman?” will have a simple answer: the taxpayer."

Saturday, September 12, 2026

Hit the Brakes Hard on Trusting Government

From Don Boudreaux.

"Here’s a letter to the Wall Street Journal.

Editor:

Peggy Noonan is so frightened of AI that she not only calls on investors to stop funding it, but on government to “hit the brakes hard” on this technology (“Pause AI for Humanity’s Sake,” September 11).

Ms. Noonan imagines AI unleashing a terrible dystopia. Yet what we imagine should be informed by the past. Ms. Noonan’s imagination isn’t. Were she to consult the past, she’d encounter a few realities beyond the obvious one that countless technologies that we today celebrate were, when introduced, reproached as imperiling humanity.

One such reality is that when insiders stir up alarm about their own industries, they’re often angling for regulation that shelters them from competition. As classic case involves AT&T: it warned that telephony would collapse into chaos unless regulated as a natural monopoly. Established bankers played the same game during the Depression, warning that, without government-imposed interest-rate ceilings, ruinous competition for deposits would breed financial crises. In each case the peril lay less in the absence of regulation than in the ‘cures’ – a fact that points to a second and more fundamental reality: a far greater danger than new technology to humanity is government authority to regulate technology.

History gives us every reason to distrust government with the awesome power to determine just how new technologies will develop, and how and when we should be permitted to uses these technologies. In short, history teaches that the wealthiest and safest societies are ones in which innovation is, as Adam Thierer calls it, “permissionless.” If we’re to hit the brakes hard, it should be on the ages-old, fear-fueled impulse to put control of economic forces and technological advances into the hands of politicians and bureaucrats."

Friday, September 11, 2026

Why Congress Shouldn’t Change SNAP’s New Payment Error Approach

By Angela Rachidi of AEI.

"Payment errors in the Supplemental Nutrition Assistance Program (SNAP, formerly food stamps) have received considerable attention in recent months. While much of the debate has revolved around the One Big Beautiful Bill Act’s (OBBBA) new requirements surrounding SNAP payment errors and the impact on states, many have overlooked the people most affected by improper payments—low-income households.

The national SNAP payment error has hovered around 10 percent in recent years, accounting for almost $10 billion in erroneous SNAP benefits yearly. Some of this is fraud, but much of it involves correctable mistakes by participants or government eligibility workers. Thanks to the OBBBA, states are now financially incentivized to lower their payment error rates because states are required to fund a portion of SNAP benefits if they climb above a payment error rate threshold.

Facing the prospect of substantial financial penalties if they do not lower their error rates, states have begun to tighten their eligibility process. As Congress works toward reauthorizing SNAP through a new farm bill, it must resist calls to weaken this cost-sharing requirement or otherwise alter SNAP’s payment error formula.

The OBBBA requires states to contribute a share of total SNAP benefits issued in their state starting in fiscal year (FY) 2028, unless their SNAP payment error rates fall below a 6 percent threshold or they are otherwise exempt. Only 10 of the 53 states or territories met this threshold in FY2025. If a similar trend holds for FY2026, states will be required to pay up to $11 billion collectively in annual SNAP benefit costs in future years. This stands in stark contrast to the period preceding the OBBBA, in which the federal government covered benefit costs entirely, leaving states to face little to no penalty for high payment error rates.

Given this blunt reality, some have called for delaying the payment error cost share or ending it entirely. Some have even suggested that states will discontinue SNAP if the payment error cost share is not delayed. Other arguments have pointed to a lack of symmetry in the payment error calculation itself, which penalizes underpayments. These arguments may fall on sympathetic ears, with Senate Republicans proposing to delay OBBBA’s payment error requirements in an attempt to pass a farm bill. However, these arguments overlook the negative effects that SNAP payment errors have on low-income families. The best approach is to leave the SNAP payment error formula as it is and fully implement the payment error cost-share requirement as OBBBA intended in FY2026.

Delaying or eliminating the cost-sharing requirement accepts the current high level of SNAP payment errors. While it is true that the vast majority of SNAP payment errors are overpayments rather than underpayments, SNAP households are still negatively affected by overpayments. For example, federal regulations require that state agencies establish a claim against households that receive an overpayment, in an attempt to collect on those claims. Once overpayments are discovered, recouping them can happen by reducing the amount of future SNAP benefits, which can put a strain on a household’s budget or potentially discourage them from participating altogether.

Although research suggests that less than 20 percent of overpayments are eventually recovered, this process can disrupt assistance, requiring recipients to submit additional paperwork or lose eligibility. Avoiding overpayments will ensure that families consistently receive the resources that they need to meet their food needs.

Furthermore, while changing the payment error formula could create symmetry in the treatment of overpayments and underpayments, the consequences of underpayments are immediate and directly harmful to low-income households. This is likely why overpayments will always be more common than underpayments. State workers may be particularly sensitive to underpayments due to the immediate consequences they can have for recipients—an important consideration for treating underpayments differently than overpayments. However, state workers also need strong incentives to avoid overpayments. Requiring a state financial contribution when payment errors exceed a certain threshold will save the federal government money, but it will more importantly avoid disrupting SNAP benefits for participating households.

The Agriculture Improvement Act of 2018 has been operating on a one-year extension since FY2023, making Congress overdue to pass a new farm bill. The farm bill not only sets agriculture policy for the country but also authorizes SNAP, including the treatment of payment errors. The House of Representatives passed a new farm bill in April 2026 that maintained OBBBA’s payment error approach, but the Senate failed to pass a companion bill even after agreeing to delay the payment error cost share. The Senate’s failure offers a good opportunity to leave OBBBA’s payment error approach as intended."

Growth through innovation bursts: Why industrial policy should not bet on size

By Giuseppe Berlingieri, Maarten De Ridder, Danial Lashkari and Davide Rigo. Excerpts:

"Industrial policy is back on the agenda across advanced economies, with a growing channelling support towards large incumbent firms on the premise that they are the most capable innovators. This column uses data on French manufacturing firms to argue that this premise deserves scrutiny. Firms become large primarily through occasional, large 'innovation bursts' rather than by innovating at persistently higher rates. The arrival of these bursts involves an element of chance, so a firm's current size says little about how much it will innovate in the future. Policies that entrench the position of incumbents may therefore slow down the churn that sustains aggregate growth."

"This column is not an evaluation of any specific industrial policy programme, and our discussion has abstracted from any strategic and security motives behind much of the current debate. Our results also do not imply that scale is never efficient: some technologies – notably intangible-intensive ones with high fixed and low marginal costs – feature genuine returns to scale and ignoring this would be costly (De Ridder 2019, 2024, Lashkari et al. 2024). Our findings do suggest that policymakers therefore face a trade-off between accommodating such scale effects, and entrenching incumbents whose size reflects the luck of past innovation bursts. An industrial policy that shields incumbents from that displacement risks slowing the growth it aims to promote." 

Thursday, September 10, 2026

Decades Of Ice-Related Climate Misinformation Drove False Claim That Glacier Collapse, Rather Than Bedrock, Caused Nepal Disaster

Egg on their faces, activist scientists and journalists are now blaming “melting permafrost,” but there’s no evidence for that either

By Michael Shellenberger

"Anthropogenic climate change caused a glacier to melt, triggering the flooding in Nepal, said scientists and journalists immediately following the disaster. “Climate change is heating up the Himalayas and supercharging the risk of disasters like the deadly flash flooding in Nepal and Tibet,” the New York Times reported on August 27 under the headline “Climate Change Raises Risk of Disasters Like Nepal Floods.” Explained the Times, “As humans warm the planet by burning fossil fuels, the Himalayas are losing their permafrost” and “the thawing permafrost is destabilizing the foundation underneath glaciers, raising the risks of precisely these kinds of landslides and glacial collapses.” It quoted Ashim Sattar of the Indian Institute of Technology Bhubaneswar: “There’s a very straight link between climate change and these types of disasters.” Alton Byers of the University of Colorado told the Times, “Permafrost has been the cryospheric glue that’s held the rock and the ice and the glaciers together for millennia, and now we’re getting increasing evidence that it’s being weakened by warming trends.” Three days later the Times told readers that “one thing seems certain: The risk of such events is increasing.”

But new satellite imagery reveals that the bedrock beneath the glacier collapsed, bringing the glacier down on top of it. “You have this big bedrock failure that took part of the glacier with it,” said geomorphologist Dan Shugar. His colleague Kristen Cook described it as “a collapse of a large piece of bedrock that was sitting below the glacier. The ground underneath the glacier collapsed and took the glacier with it.” Another glaciologist, Jakob Steiner, agreed, explaining that “You basically had the lower part of a glacier tongue that sheared off because the rock below failed.” Cook told the New York Times that “The rock that the glacier was sitting on collapsed,” and yet the Times headline is “Landslide Along With Glacial Collapse Likely Set Off Nepal Flooding, Scientists Say,” which is misleading in that it was the landslide that brought down the glacier. “Essentially, a chunk of the mountainside collapsed,” Shugar told the Times."

Wednesday, September 9, 2026

Capital Is Not Taking Half of America’s Income, and Other Myths About the “Labor Share"

By Richard DiSalvo, Erica York.

"Economists and journalists have been pointing to a labor share of income series from the Bureau of Labor Statistics (BLS) as evidence that capital is taking an ever-increasing slice of the economic pie. By that series, labor’s share fell from nearly two-thirds in the 1950s to about half today, fueling headlines like “US workers’ share of national income falls to a new low.” 

But a closer look at the national income accounts shows a different story. Labor’s share is both higher and more stable than the BLS series suggests.

Capital Takes Between 17 and 24 Percent, Not Half, of Gross Income

Most recently (Q2, preliminary), the BLS series reports 53 percent of income accrues to labor, leaving 47 percent to nonlabor, which commentators call “capital” or “owner” income. But in that commentary, the definitions of income and the underlying assumptions BLS uses to split it often go unclarified. We untangle those assumptions below; but first, we build directly from the national accounts to show how total US income divides to capital and labor, then contrast that with the BLS series.

Gross domestic income totaled roughly $32.2 trillion at an annual rate in the second quarter of 2026. Of every dollar, 50.4 cents were paid to workers as compensation: 41.5 cents of wages and salaries plus 8.9 cents of benefits. This is unambiguously labor income. But it does not necessarily follow that all 49.6 cents of the “nonlabor” income accrue to capital.

The income unambiguously paid to capital includes corporate profits after corporate tax, interest, and rents, and this amounted to nearly 17 cents. About 3.6 cents of that is “imputed rent,” an estimate of what homeowners would pay to rent their own homes. Imputed rent is not actually cash that people collect and is not what people typically think of as “capital income.”  (The national accounts also include the “current surplus of government enterprises,” which operate at a loss, and thus account for a small, negative value, which we exclude.)

Another 6.7 cents were the income of proprietorships and partnerships, a mix of pay for the owners’ work and return on their investment. If this is entirely attributed to return on investment, capital would still only earn 24 cents per dollar of gross income—far less than half.

Gross Income Overstates What Households Actually Receive

The remaining categories of “income” deserve a closer look, because they aren’t income that accrues to anyone.

Depreciation takes nearly 17 cents of every dollar. This is the cost of replacing worn-out buildings, equipment, and software; each year, this spending returns the capital stock to where it started, and it never makes its way to a paycheck or a brokerage account.

Taxes are collected before income ever reaches a household: 7.0 cents in taxes on production and imports (TOPI, including sales and property taxes, federal excise taxes, and customs duties net of subsidies) plus 2.8 cents in corporate income taxes.

Using a gross measure to attribute non-labor income to capital counts these categories as accruing to capital even though they never show up as capital income. That creates a particularly odd position for many commentators when it comes to tariffs. Every dollar of tariff revenue mechanically raises the “nonlabor” share of income and is thus categorized as “capital income.” Analysts’ interpretations of tariff incidence vary, but no common interpretation considers tariff revenue to be capital income.


Labor’s Share of Net Income Is Within Historical Levels

Removing depreciation and taxes leaves net income. In the second quarter of 2026, that leaves roughly $23.7 trillion of private sector income that was actually paid out to people.

A leading literature survey on the labor share distinguishes between income that unambiguously belongs to labor (employee compensation), income that unambiguously belongs to capital (profits, interest, and rent), and the ambiguous remainder (proprietors’ income, after excluding taxes). Tracking these three categories as shares of net income since 1947 tells a clean story and changes the picture substantially from the headlines.


Unambiguous labor income has made a round trip: it was about 69 percent of net income in the late 1940s, rose to about 75 percent in the 1970s, and is 68.3 percent today. Labor share, in other words, is not at a “never before seen” level.

Unambiguous capital income has risen from about 13 percent of net income in the late 1940s to 22.6 percent today. More than half of that rise has come since 2000, when it stood at 17 percent, with the largest jump coming during the pandemic years of 2020 and 2021 (before the release of AI tools).

The ambiguous proprietors’ slice fell from about 18 percent of net income in the 1940s to about 10 percent by 1970, driven largely by the decline in farming. It fell to a low of around 6.7 percent in 1982, then recovered to roughly 9 percent to 10 percent, most recently measuring 9.1 percent.

The nature of proprietors’ income is ambiguous. Assign it entirely to labor, and capital’s share stays at 22.6 percent of net income, the “unambiguous capital share” in the nearby chart. Or assign it all to capital, and capital’s share rises to 31.7 percent of net income—this is the approach we take to reach the highest capital share we can infer. The truth is somewhere in between, but recent research suggests proprietor income is mostly labor, so even our 31.7 percent estimate—still far below half—is likely too high.

Because proprietor income has been a relatively stable share since the late 1980s, no fixed (time-invariant) allocation of it between labor and capital can drive recent trends, although an allocation that itself changes over time can. A time-varying allocation is one of several drivers of the BLS trend, which we discuss next.

Estimating Labor Share and Assumptions Behind the BLS Approach

A labor share estimate requires dividing income into two categories: labor and capital.

In the corporate sector, the split is easy: wages on one line, profits on another. Indeed, some economists restrict their analysis to the corporate sector for this reason. For noncorporate businesses, it must be estimated, since their income is a mix of labor and capital. Government, nonprofits, farms, and the imputed rent on owner-occupied housing are often excluded.

Every published labor share estimate must make assumptions about noncorporate actors, and these assumptions can move the level and trend.

The BLS measure uses an imputation strategy to split the noncorporate business sector into labor and capital income, producing a time-varying allocation. It only covers the nonfarm business sector, or about three-quarters of the economy. This contrasts with using the national accounts, which keeps all income under one fixed convention.

Let’s start with the BLS split of proprietor income. BLS assumes proprietors “pay themselves” the average hourly compensation of employees in the sector times their hours, and treats whatever is left as capital income. Because hours per worker move slowly, this is essentially a comparison of two averages:

The result has shifted enormously; we estimate BLS’s inferred capital share of proprietors’ income rose from less than a fifth in 1990 to about half today, in line with trends documented by Elsby, Hobijn, and Åžahin through 2012.

Then let’s look at the omissions. Government and nonprofits, roughly 15 percent of the economy, are excluded; including them, as BLS economists note, would increase BLS’s estimated labor share. Farms are also excluded; this matters little today but makes historical comparisons anachronistic, as farm proprietors’ income was 6 percent of the total in the late 1940s.  

Finally, the BLS ratio divides income-side compensation by product-side output, so the bookkeeping gap between GDP and GDI (the “statistical discrepancy”) can affect the trend. Our approach uses the income accounts throughout, so all components sum to total income by construction.

Correcting the Headlines

The description of the labor share as “unprecedented” or “record low,” the “close to 50-50 split,” and the commonly shared figure depicting a trend downward since the 1940s are all misleading. Labor earns about half of every dollar of gross income, but the remainder should not all be attributed to capital—much of what is counted in gross income does not accrue to anyone. A better measure uses net income, and the share of net income accruing to capital is between 22.6 percent and 31.7 percent, depending on how proprietors’ income is treated. The labor share is back to a historically precedented, not “never-before seen,” level. And the “downward trend throughout” needs to be replaced with “the labor share rose, then fell, over the postwar era.” It has made a round trip, rather than declining consistently from its starting level."

Tuesday, September 8, 2026

Welfare Digest | Welfare Reform's Success Holds Up 30 Years Later

Romina Boccia and Tyler Turman of Cato.

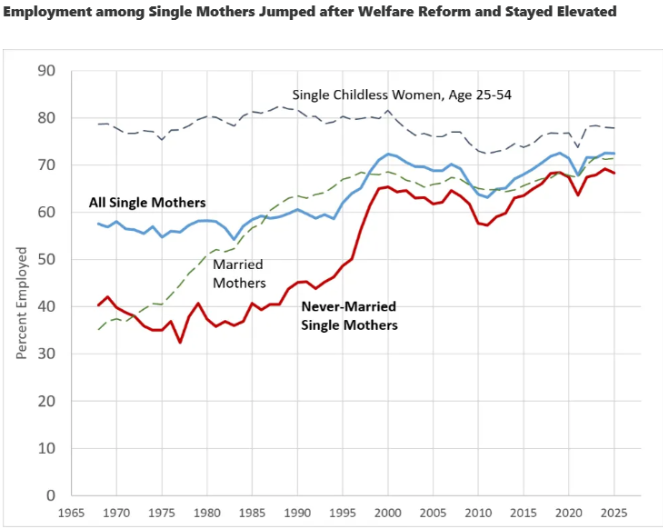
"Welfare Reform's Success Holds Up 30 Years Later. The positive effects of the 1996 welfare reforms on work and poverty still hold three decades later, argues AEI scholar Scott Winship. At a recent House Work & Welfare Subcommittee hearing, Chairman Darin LaHood (R-IL) noted that the law replaced “an open-ended 'no strings attached' cash entitlement” with a program that “included work requirements, time limits, enforced the principle of work in exchange for benefits, and capped federal funding for benefits.” In his testimony before the committee, Winship pointed out that child poverty fell by roughly half to more than three-quarters between 1996 to 2022. As Winship says, earnings among families with children since welfare reform have grown so large, that “if the entire safety net disappeared tomorrow, the child poverty rate would still be lower than in 1993.” Winship credits part of this to the employment gains after welfare reform, especially among single mothers, which rose so dramatically that they have “never returned to pre-[reform] levels. Even in the depths of the Great Recession, single mothers were more likely to be employed than they had ever been before 1995.” To read more about the impacts of welfare reform, including how states circumvented the law’s spending constraints by shifting beneficiaries off TANF and onto other, open-ended entitlements, read the statement we submitted for this hearing here."